Two Wall Street Firms Raise AMD Stock Price Target To $700
Two major Wall Street firms have raised their price targets for Advanced Micro Devices, with Stifel Nicolaus moving to $700 and Mizuho Securities increasing their forecast to $705 amid strong artificial intelligence momentum.

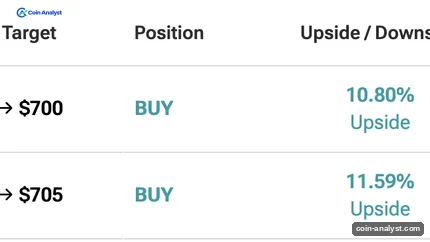
Advanced Micro Devices, Inc (AMD) remains a prominent choice among Wall Street analysts. Ruben Roy of Stifel Nicolaus has increased AMD’s price target to $700 from $635, representing a potential 10.80% upside from present price levels. At the same time, Vijay Rakesh from Mizuho Securities has lifted their forecast from $580 to $705, marking an upside of roughly 11.60%. Here is a closer look at the driving forces behind Wall Street’s upward revisions for AMD.
Why Is Wall Street So Bullish On AMD Stock?
Over the past year, AMD has ranked among the market’s top-performing equities. The artificial intelligence boom stands out as one of the most successful chapters in the firm’s history. As a direct competitor to market leader Nvidia (NVDA), AMD stands out as one of the few players taking the fight to the industry giant. Although alternative chipmakers like Intel exist, AMD has positioned itself as the primary challenger. This dynamic makes the company highly appealing to Wall Street, as competition frequently drives enhanced innovation and stronger returns. Analysts appear to be wagering that AMD will maintain its momentum amid the ongoing AI wave.
The upcoming release of AMD’s third-quarter financial results is scheduled for November 3, 2026. Numerous observers expect robust revenue from the firm’s Helios chip sales to show up in these November figures. Consequently, these target adjustments may reflect analysts updating their stances prior to the Q3 report. It is entirely possible that additional financial institutions will mirror the actions of Stifel Nicolaus and Mizuho Securities by upgrading their price targets for AMD.
Also Read: Ark Invest Buys $81 Million Nvidia Stock, Sells $110 Million AMD
Currently, AMD’s data center division serves as a primary revenue driver. Driven by sustained demand for AI model training, this trajectory is expected to persist in the years ahead. Data centers will likely remain the top-earning segment for AMD in its upcoming financial statements. Expanding data center operations serve as a key motivation for analysts maintaining an optimistic outlook on the stock.